Roof insurance guidance for Sapulpa, OK
Separate the roof repair from the coverage decision. Understand deductibles, depreciation and the steps between a reported loss and payment.
Understand what the policy pays for
Insurance coverage depends on the policy and the cause of the loss. A roof’s age, a nearby storm or a replacement recommendation does not by itself establish that the insurer owes for a new roof. The physical condition and the covered event need their own assessment.
Once a claim is evaluated, the payment can still differ from the full roofing price. Deductibles, depreciation, coverage limits and the approved scope affect what is paid and when. A replacement-cost policy may have conditions for releasing part of the settlement after work is completed.
This guide explains those distinctions so the repair conversation can stay clear. Sapulpa Roofing Co helps with the roof’s physical needs; the insurer makes the policy and claim decisions.
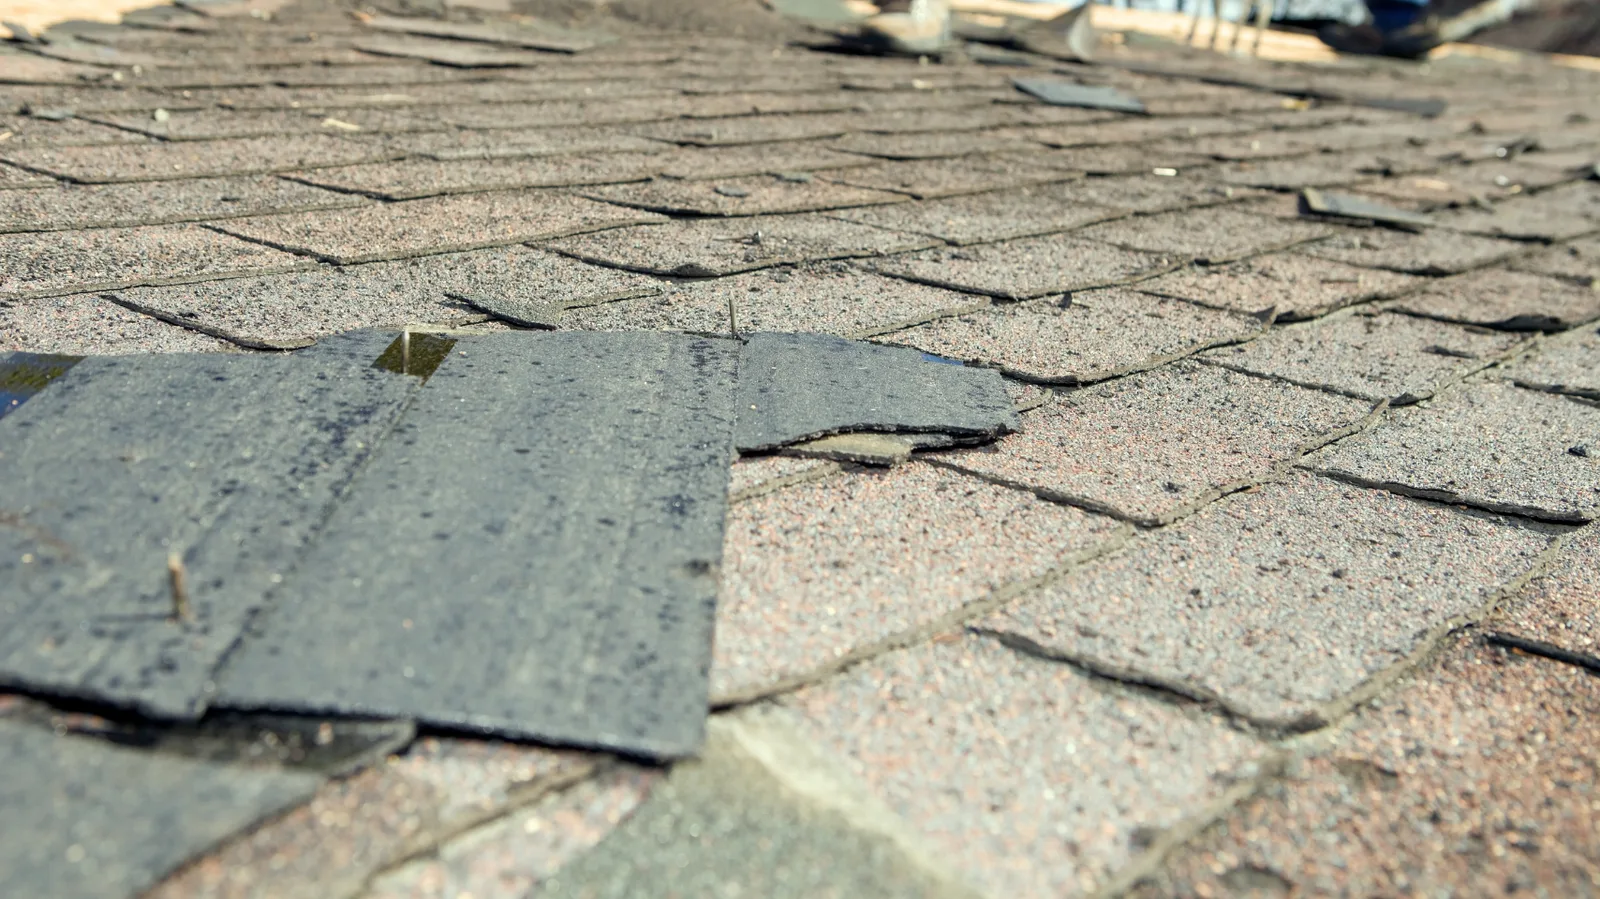
From roof damage to an insurance decision
The Oklahoma Insurance Department’s consumer FAQs explain the distinction between actual cash value and replacement-cost coverage. Your own policy controls the terms.
- Address immediate exposure safely
Keep people away from unsafe areas and arrange necessary temporary protection where conditions allow. An active opening needs attention even while coverage is being reviewed. Save receipts and existing photographs of protective work without taking risks to gather them.
- Notify the insurer
Report a potential covered loss promptly under the policy’s instructions. Describe what you observed and when. A roofer’s view of damaged material can inform the physical scope, but it does not replace the insurer’s coverage review.
- Distinguish inspection from settlement
The adjuster evaluates the claim under the policy. The roofing scope identifies damaged covering, underlying layers, flashing and other work needed at the property. An agreement on one figure does not automatically resolve every difference in scope.
- Plan the permanent work
Connect the roofing proposal with the actual condition, including any concealed damage discovered later. Keep changes and the owner’s payment responsibility clear before authorizing additional work.
Deductible, depreciation and replacement-cost payment
For example, an insurer may approve covered replacement work but issue an initial payment after subtracting the deductible and depreciation. If the policy permits recovery of that depreciation, later payment depends on its conditions. That sequence is different from a guarantee that every project expense will be reimbursed.
The roofing work and the claim are separate decisions
A roof can need work even when the loss is excluded or the payment falls below the repair price. A coverage decision also does not mean that any chosen upgrade belongs in the settlement.
- Cause and exclusions
Ordinary wear, installation defects and a covered weather event can lead to different policy outcomes. The roof inspection should describe the condition without promising which cause the insurer will accept.
- Covered scope and proposed work
The insurer may allow a defined repair while the owner considers a broader replacement or material change. Keep the required work, any optional changes and their payment responsibility distinct.
- No automatic zero-cost outcome
The deductible, uncovered items and contract terms can leave an owner balance. Do not assume the deductible disappears or that a roof inspection guarantees a claim result.
Roof Insurance FAQs
Does insurance replace a roof because it is old?
Age alone does not create a covered loss. The policy, cause of damage and exclusions govern coverage, while the roof’s condition determines what physical work is needed.
Does replacement-cost coverage pay everything up front?
Not necessarily. An initial settlement may subtract deductible and depreciation, with eligible depreciation recoverable only after policy conditions are met. Limits and deadlines still apply.
Can I protect an active roof leak before the claim is settled?
Necessary temporary protection can be arranged while a claim is being reviewed, subject to safe access and the policy’s instructions. Notify the insurer promptly and retain available documentation and receipts. Do not wait in an unsafe situation merely to preserve a claim inspection.
Get help with the roof work in front of you
Get a clear view of the roof work before treating a payment figure as the project scope. Request a free inspection for the damage or leak you have noticed.